Arm Shares Dip Despite Exceeding Q2 Expectations, Future Outlook Modestly Surpasses Forecasts
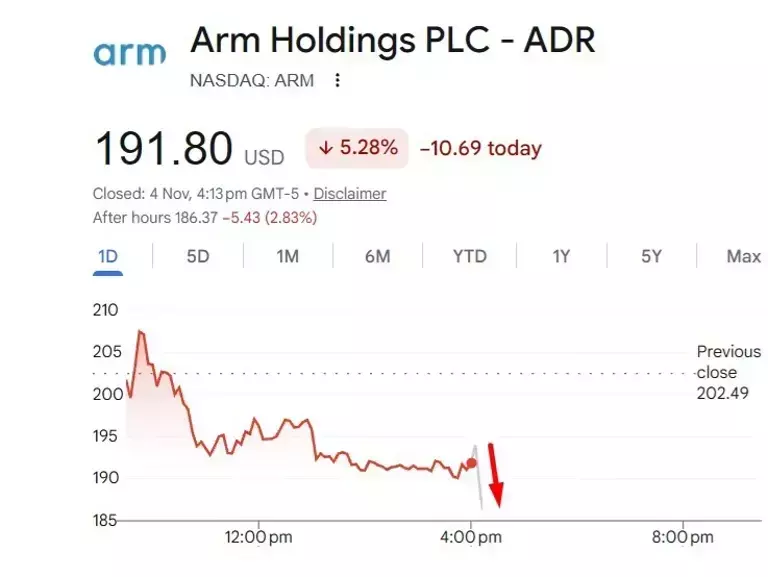
Exceeding Expectations, Yet Falling Short: Arm's Post-Earnings Paradox
The High Bar of Investor Expectations
Arm's stock saw a 5% decline in after-hours trading, a surprising outcome given that the company surpassed both its earnings and revenue targets. This market reaction underscores the elevated expectations placed on growth-oriented companies, particularly those linked to the artificial intelligence sector. When a company with such a premium valuation delivers guidance that merely aligns with consensus, rather than significantly exceeding it, investors tend to react with disappointment.
Fiscal Q2 Highlights: A Strong Performance
For its fiscal second quarter, Arm reported an adjusted earnings per share of 52 cents, outperforming the analyst consensus of 47 cents. Revenue also impressed, reaching approximately .44 billion, which was above the estimated .38 billion. This represents a beat of over 4%, showcasing the company's robust operational performance.
Q3 Outlook: A Modest Edge Over Forecasts
Despite the strong Q2 results, the fiscal third-quarter guidance proved to be a point of contention for investors. Arm projected revenue between .49 billion and .59 billion, with the midpoint of .54 billion slightly higher than the .53 billion consensus. Similarly, adjusted EPS guidance of around 56 cents barely surpassed the 55 cents anticipated by analysts. This marginal outperformance, combined with an annualized contract value that was slightly below expectations, contributed to the stock's negative performance.
The Importance of Annualized Contract Value (ACV)
The annualized contract value, a crucial metric reflecting licensing commitments, came in at approximately .79 billion, just below the anticipated .80 billion. While this miss was minor, it highlighted a sensitivity among investors who demand consistent and strong growth from companies like Arm, especially given their high valuation multiples. Any deviation from aggressive growth trajectories can trigger a reassessment of investment potential.
Strategic Initiatives: AGI CPU and Arm-based PCs
On a more positive note, Arm's management shared encouraging updates on its strategic initiatives. Purchase orders for the AGI CPU, a data center processor, now extend through calendar year 2027, with commercial deliveries slated to commence in the fourth quarter. This move signifies a strategic shift for Arm, traditionally a licensor of designs, towards directly impacting the chip market. Additionally, Arm-based chips achieved a significant milestone, with over 10 billion units shipped in a single quarter, and now power approximately 20% of global PC shipments, demonstrating the architecture's expanding presence beyond smartphones.
Navigating the Future: Growth Justification and Market Sensitivity
The market's reaction suggests that investors are closely scrutinizing Arm's ability to translate its technological advancements into substantial financial growth. The success of the AGI CPU's commercial rollout and its contribution to future revenue will be pivotal in justifying Arm's premium valuation. In a market where AI-linked chip companies are highly valued, any indication of growth slowing or merely meeting expectations can lead to immediate investor repositioning.